


WESTMINSTER, Colorado — The time to start planning for your company’s 2028 health benefits? January of 2027.
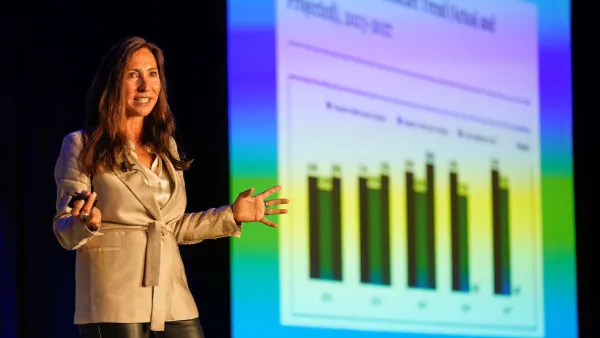
That’s according to Marybeth Gray, senior VP of health and welfare benefits consulting with Marsh McLennan Agency. Speaking to a crowd of finance leaders at the CFO Leadership Council’s fall conference in Colorado this week, Gray urged attendees to start thinking about health benefits as soon as feasibly possible.
What might have long been considered strictly an HR issue, Gray said, has firmly become a finance issue.
“We need to get on solid footing,” she said, citing data from the Business Group on Health showing that healthcare costs have ticked up as much as 76% over the last decade.
Gray’s message likely didn’t come as a surprise to the conference’s more than 300 attendees. A familiar face on the CFO conference circuit, she has been regularly sounding the alarm about the ongoing rise in healthcare costs for a while now. Over meals at the conference, attendees commiserated about the rising healthcare costs, which have been described as a “tapeworm” in the American economy by investor Warren Buffett.
Speaking at the Westin Westminster hotel on Tuesday, Gray offered a few tips to help keep costs at bay and employees healthy:
1. Plan early, and don’t fear change
If you begin planning for next year’s health benefits in summer, Gray said, it’s already too late. “June is implementation time,” she said.
Sometimes, early planning could reveal that it’s time to switch carriers altogether. Such moves are typically heavy lifts and may not be initially popular, but they could pay off in the long run.
Without endorsing any particular carrier, Gray pointed to General Motors’ recent decision to drop Blue Cross Blue Shield of Michigan and switch to Aetna.
“You’re going to hear ‘it’s not a good time,’” Gray told attendees. “But we can’t stand still because healthcare costs don’t stay flat, and choosing not to act is actually a decision.”
2. Manage ‘high-cost claimants’ better
Wellness programs tend to be popular among employers, but, in Gray’s view, they aren’t likely to move the needle on costs in the long run. “The people who participate in wellness programs and run and do all the things you want them to do are not the population that are driving costs,” Gray said.
That’s not to say employers should consider forgoing such plans; they’re still an important part of a workplace culture, Gray said. But companies should look into ways to “engage” employees with chronic conditions that drive up costs. She pointed to diabetes management, for example. Employees with the condition could be auto-enrolled with coaches to help manage it.
“If you really want to get to a strategy that’s going to deliver the most value to your bottom line, it’s looking at your high-cost claimants and your top utilizers,” Gray said. “That’s the data you want to be asking your carrier partners for in January.”
3. Take advantage of medical advances
Few would disagree that there’s a fundamental mismatch between the way health insurance is administered and the state of modern healthcare. As Gray put it: “The science is George Jetson; the benefits are still Fred Flintstone.”
She pointed to a range of advances that could, in theory, help address major health issues before they eat up budgets. Genomic testing is one. Such tests essentially evaluate an individual’s genes to see if they’re at risk for certain types of cancers. Health plans that cover such tests might help protect employees and ultimately trim costs.
Then there’s pharmacogenomic testing, which can help people find which medications might work best for their individual conditions.
“Why aren’t we incorporating some of this stuff?” Gray asked.